THE SHORT ANSWER
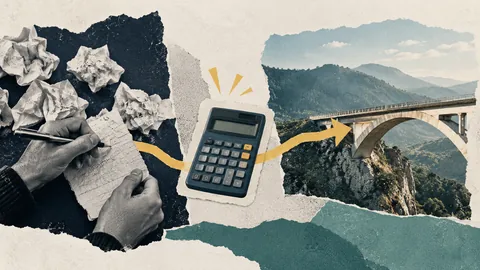
Content costs become more useful when you estimate the complete workflow rather than the writing assignment alone. Define a usable deliverable with an inspectable scope, estimate the role hours needed to produce it, and add external expenditure and planned maintenance. Separate initial production from recurring effort, and observed timings from assumptions. This article develops an editorial planning model for B2B teams; it does not supply market rates or universal productivity targets. A cheap draft is not economical when expert review, corrections or poor usability remain hidden. The relevant unit is the work required to deliver an accepted, usable asset.
To see how this step fits into your content strategy, read the pillar guide Content marketing for B2B SaaS: strategy, formats and qualified demand.
Define the deliverable being costed
Describe the object so two people understand the same scope. “One whitepaper” is insufficient. Record the buyer task, required evidence, approximate information depth, languages, design work and acceptance criteria. Distinguish original investigation from repackaging sources that have already passed review. The resulting documents might look similar while requiring very different amounts of work from the team. Explore this further in the guide Blog, documentation or help centre: assign content to its purpose.
State what the assignment includes and which changes trigger another estimate. A new audience, unresolved competitor comparison or additional approver changes the work. Do not cost the cheapest imaginable execution while promising a more demanding version. The model starts with a recognizable unit of delivery, rather than a desired low total that is made to appear feasible through increasingly optimistic assumptions about effort and availability.
Expose the complete production path
Break production into research, expert contribution, structure, drafting, factual review, editing, design, technical publication and acceptance. Identify translation, source clarification and accessibility review separately when needed.
For each handover, distinguish active effort from waiting time. Both affect the delivery date, but a week awaiting feedback is not automatically a week of full-time labour. Actual coordination effort should still be counted. Attach activities to named roles so the same expert review is not charged once under editorial and again under the product team. The estimate must describe who does the work, not merely reproduce departmental labels.
Which work is missing from the writing brief?
This is a list of material activities, not a requirement to time every minor action. Use a level of recording that reveals important drivers without turning the content process into administrative work for its own sake.
Assign hours and rates consistently
For every role record estimated hours and an agreed internal cost rate or specific external quotation. Ask finance what the internal rate includes. Shared tools and overhead should not appear in full within the rate and again as a separate flat charge. Apply consistent definitions when comparing work inside the same model, and keep different costing perspectives visibly separate.
Calculate hours multiplied by rate for each role, then add distinctly allocated external expenditure. Mark unknown positions as unresolved rather than allowing a blank field to mean free labour. GOV.UK discusses cost per transaction as a defined cost for completing a service task. Here we borrow only the principle of an explicit delivery unit. This does not make government transaction accounting a ready-made accounting standard for your content operation. Explore this further in the guide Gated or ungated: decide how buyers access B2B resources.
| Review field | Evidence or observation | Next decision |
|---|---|---|
| Output | Consistent cost scope and assumptions | Compare baseline with justified extra work |
| role hours | Consistent cost scope and assumptions | Compare baseline with justified extra work |
| maintenance | Consistent cost scope and assumptions | Compare baseline with justified extra work |
Model rework and uncertainty explicitly
Estimate a reasoned base case and an adverse case. Change concrete drivers: another expert round, a missing source, substantial translation correction or a new product version. An unexplained contingency allowance makes uncertainty less useful than a short list of plausible triggers. State what additional information would narrow the range and who can obtain it before the work is committed.
Rework caused by changed scope should be distinguished from avoidable quality correction. Both consume time but require different responses. One may need a scope decision; the other may need a better brief or earlier factual review. Use observations to improve the process rather than to assign blame. Pause a fixed commitment where an essential review effort still depends on sources or expertise that are not available to the team.

Fictional calculation for a specialist guide
Assume the invented SaaS business Klarpfad plans an integration guide. For illustration only, it estimates twelve research and editorial hours at an internal rate of €70, four expert hours at €90 and €300 of design expenditure. Assumed production cost is €1,500. These figures are fictional inputs, not recommended fees or customer results. An additional approval round is not included in this first calculation.
For the following six months the example adds two factual reviews requiring three hours in total at €90. The initially considered lifecycle therefore costs an assumed €1,770. If a product change removes the guide's usefulness, the production figure alone is an inadequate comparison. Before commissioning, the team checks expected validity and the maintenance commitment it can actually support. It does not derive guaranteed returns from merely publishing the document.
Cost reuse as incremental work
Allocate shared research to a parent topic and then estimate the additional effort for each output. A LinkedIn post derived from a guide may require a new angle, design, context review and approval.
Count derivatives that have actually been accepted and made usable. Ten automatically generated drafts are not an economic benefit when nine remain unreviewed. Compare a small, fully supported series with the alternative of separate productions. Ask whether another output serves a meaningfully different reader task. Increasing the number of pieces does not justify expenditure where material merely repeats the same point and creates additional review and maintenance obligations.
What effort remains when reusing content?
Call this incremental work. If you need format-level comparisons, distribute shared costs using an explicit allocation rule. No allocation method makes the original research retrospectively free.
Connect cost to use without inventing impact
After publication add observed usage, questions and concrete sales applications. Cost per download or visit can be useful calculation views, but neither by itself establishes quality or incremental revenue. A specialist guide used by a few qualified evaluation groups should not automatically lose against a general reach article. Compare work with similar purposes and reasonably comparable observation periods before interpreting the numbers.
If reporting pipeline involvement, state the association rule and known gaps. Do not call the full value of every influenced contract a content return. A buying group may also have used events, sales conversations and several resources. GOV.UK recommends combining data sources for service evaluation; our editorial application combines analytics with usability and team observations. That is a practical decision framework, not causal proof derived from a traffic count.
Calibrate using an actual assignment
Select an upcoming assignment and record only the material roles and handovers. After acceptance compare estimated effort with what actually occurred. Investigate the largest discrepancy first: additional scope, unavailable expertise, unclear review or an underestimated publication path. Update the corresponding assumption for the next comparable assignment and preserve the earlier estimate so learning remains inspectable.
Assign someone to review effort after publication as well. A model becomes systematically misleading if it captures manufacturing reliably while ignoring subsequent maintenance. Set a review date and decide whether to continue, simplify or retire the asset. The aim is a better resource commitment under known limitations. It is neither exhaustive surveillance of individual employees nor a universal price list capable of deciding the cost of every future content format without further investigation.
INTERACTIVE / FROM READING TO ACTION
Three checkpoints for your implementation
Choose a checkpoint and track your reading progress. Checks are neither saved nor sent and do not score your business.
CHECKPOINT 01
Assign hours and rates consistently
For every role record estimated hours and an agreed internal cost rate or specific external quotation.
Explore in the article ↗CHECKPOINT 02
Model rework and uncertainty explicitly
Estimate a reasoned base case and an adverse case.
Explore in the article ↗CHECKPOINT 03
Fictional calculation for a specialist guide
Assume the invented SaaS business Klarpfad plans an integration guide.
Explore in the article ↗Frequently asked questions
What is the appropriate cost unit?
An accepted deliverable with a clear purpose and scope. A draft alone is insufficient when factual review, design or publication remains unfinished.
How should internal expert time be treated?
Record the effort actually required using the agreed internal rate. Clarify what the rate includes so identical work is not counted more than once.
Does waiting time equal labour time?
Not automatically. Waiting affects elapsed delivery time. Estimate committed labour and actual coordination separately instead of charging every calendar week as full-time work.
Are AI-generated drafts free outputs?
No. Include review, revision and acceptance work. The economically relevant outputs are usable, accepted assets rather than the number of text files generated.
Can a download prove a financial return?
A download describes an action. Economic interpretation needs other observations and an explicit association rule; direct revenue causation does not follow from that action.
When should an estimate be reopened?
When audience, evidence, languages, product version or review effort changes materially. Record the trigger and revised assumption before making another commitment.